
Monday Brief No. 2, Canada edition
The Bank of Canada raised rates. What it costs you
Figures checked Read the US edition
In this issue
2 min read
The Bank of Canada raised its rate to 2.50%
Plus!
- The federal budget comes out Thursday, Nov 5.
- Big-bank savings accounts still post 0.01%.
This week
Must-read this week
The federal budget comes out Thursday, Nov 5.
Finance Minister François-Philippe Champagne tables Budget 2026 on Nov 5. The government says it will focus on investment, jobs and making life more affordable.
What it means for you: Budgets can change tax credits, benefits and housing programs. Check what's new for your household after Nov 5.
Source: Department of Finance Canada
Big-bank savings accounts still post 0.01%.
The six big banks' typical posted savings rate is 0.01%, and their 1-year GIC pays 2.45%. The Bank of Canada's own deposit rate rose to 2.45% on Oct 28.
What it means for you: If your savings sit in a big bank's basic account, check its rate. High-interest savings accounts and GICs pay much more.
Source: Bank of Canada
Posted 5-year fixed rates held at 6.19%.
The big banks' typical posted 5-year mortgage rate was 6.19% in the week of Oct 28, unchanged since early October. Their posted 1-year rate is 5.49%.
What it means for you: Fixed rates follow bond yields, not the Bank's rate. If you renew soon, posted rates are a ceiling: ask your lender what it will actually offer.
Source: Bank of Canada
The numbers
This week’s rates
Inflation, September
3.1%
August was 3.0%
Statistics CanadaBank of Canada rate
2.50%
up from 2.25% on Oct 28
Bank of CanadaPrime rate
4.70%
4.45% before the hike
RBC Royal Bank5-year mortgage, posted
6.19%
unchanged since early October
Bank of Canada
The Big Money Move
The Bank of Canada raised its rate to 2.50%
The Bank of Canada raised its rate a quarter point to 2.50% on Oct 28, its first move since October 2025. It said high energy prices risk spreading to other prices. The US Fed held the same day. The Bank decides next on Dec 9.
Prime follows the Bank.
The big banks' prime rate was 4.45% before the hike and is 4.70% now. Lines of credit, HELOCs and variable mortgages are priced off it.
What it means for you: Those bills cost more from the next statement. On a fixed-payment variable mortgage, the payment may stay put while more of it goes to interest.
Inflation is the reason.
Prices rose 3.1% in the year to September (Statistics Canada). The Bank expects about 3.5% by the end of the year and 3% on average in 2027, and said it may need to raise again.
What it means for you: Another hike is possible on Dec 9. Paying down variable-rate debt now lowers what the next one would cost you.
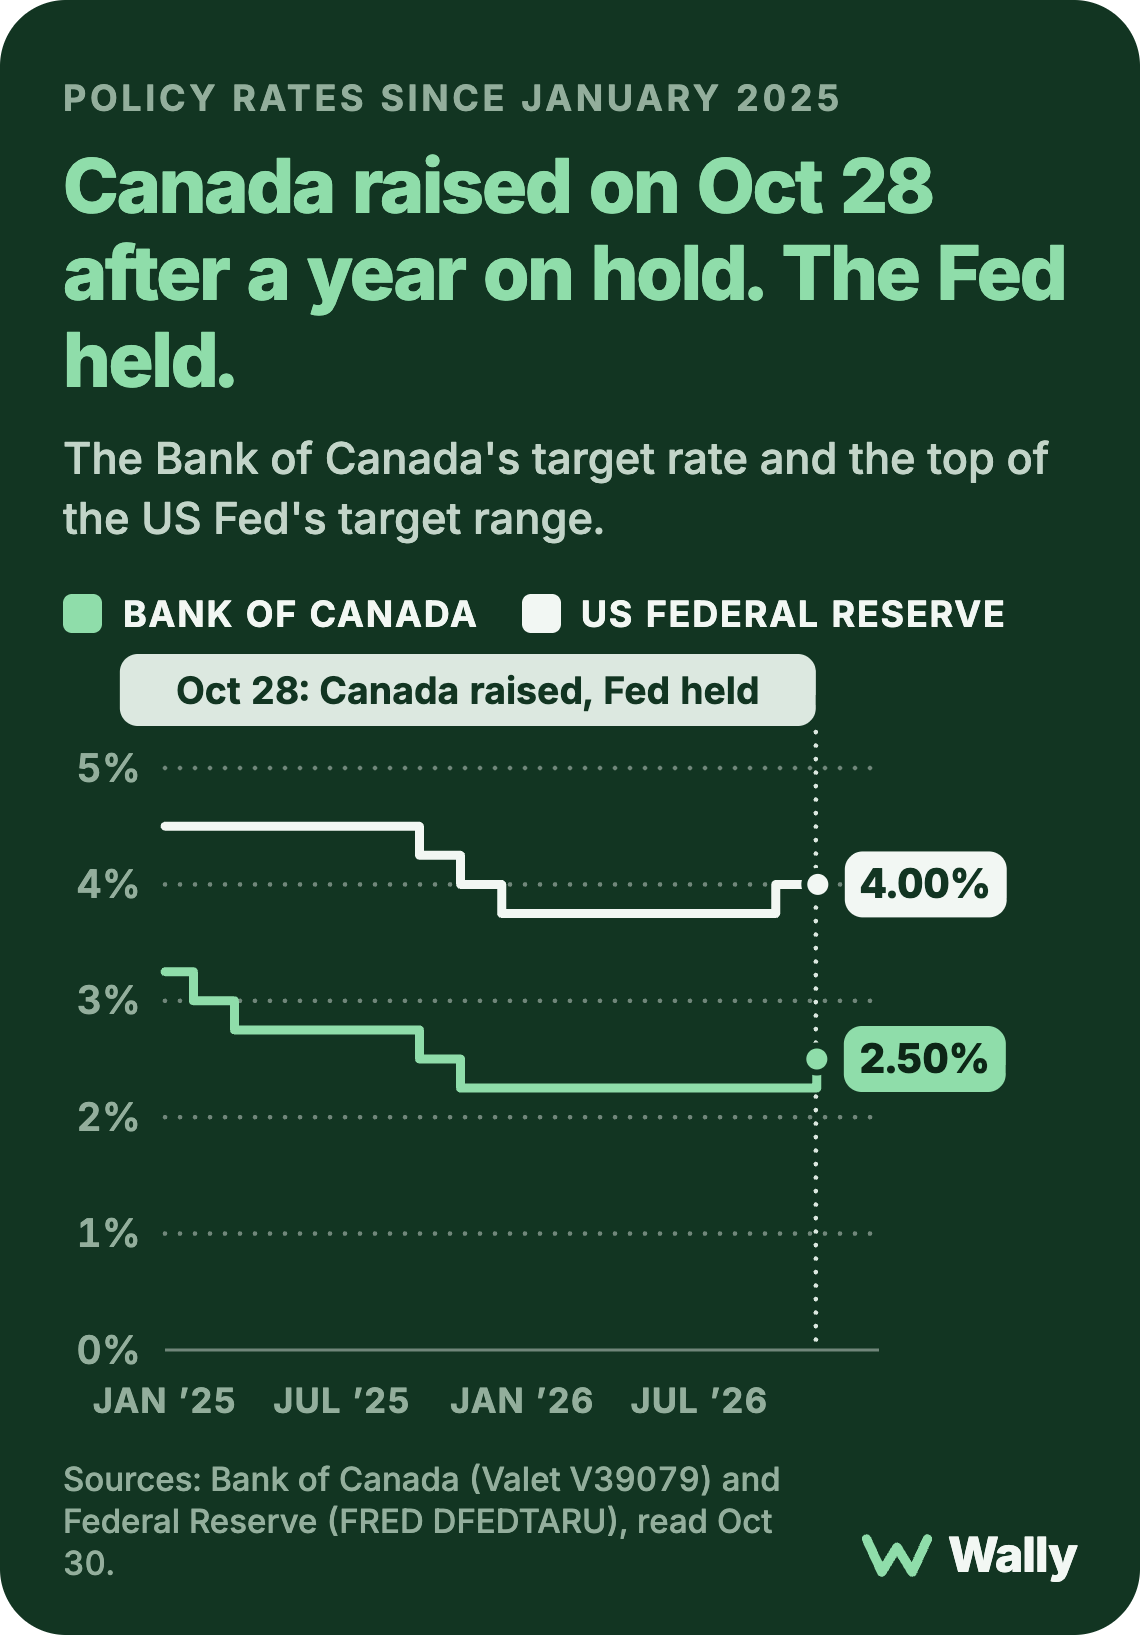
Chart source: Bank of Canada (Valet V39079) and Federal Reserve (FRED DFEDTARU), read Oct 30.
Wally can do this
How a GIC ladder works
A GIC locks your money at a set rate for its term, and most can't be cashed early. Split your savings across GICs that end a year apart, and one comes due each year: you can use that money, or reinvest it at that year's rate. If rates rise, part of your savings catches up every year.
Put it in your calendar
Coming up
- Federal budget
- Jobs report · 8:30am ET
- Ontario Trillium Benefit payment
Sources
- Bank of Canada: rate announcement
- Bank of Canada: policy rate
- Statistics Canada: CPI
- RBC Royal Bank: prime rate
- Bank of Canada: posted rates
- Bank of Canada: posted rates and rate announcement
- BMO: mortgage rates
Every figure checked against Bank of Canada, Statistics Canada, RBC Royal Bank and BMO on Oct 31, by Meet, Wally's founder.
General information, not financial advice. Figures can change after the day they were checked; the linked sources are the final word.
Get the Monday Brief every week
It comes with Wally, the AI agent that finds what’s costing you money. Seeing what it finds is free. See past issues.

